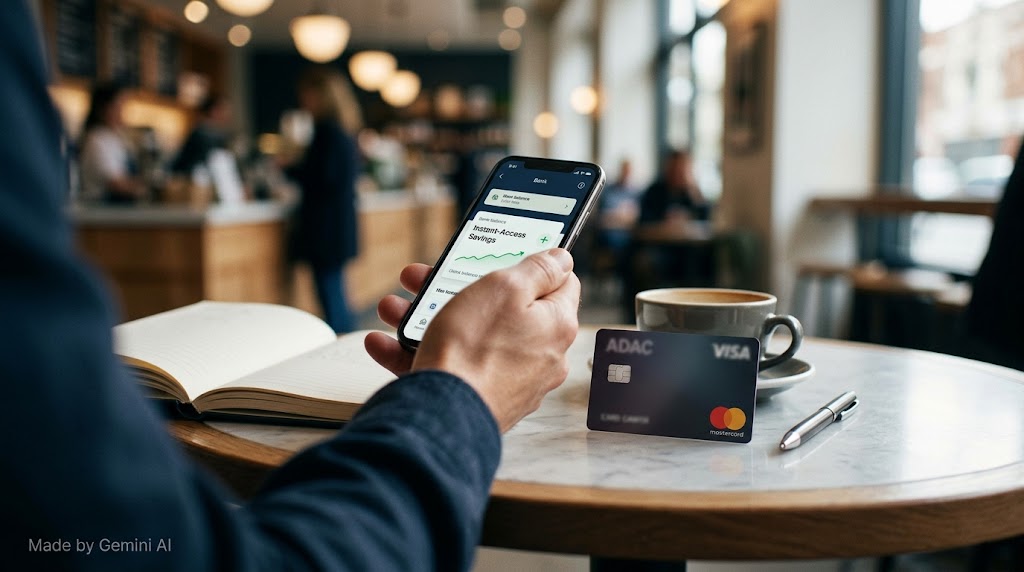
Solaris, the Berlin-headquartered Banking-as-a-Service provider, has added an instant-access savings account to the ADAC credit card portfolio, extending a partnership that has grown steadily since Solaris took on the programme. The product, known in Germany as a Tagesgeldkonto, follows a soft launch in September that made it available to 50,000 ADAC cardholders ahead of the full portfolio rollout.
The account sits alongside the existing credit card account and can be opened digitally in a few steps. Onboarding requires IBAN linking and two-factor authentication. Deposits and withdrawals are processed either via the ADAC credit card account or a designated reference account, and deposited funds remain available daily.

At launch, new customers receive a promotional interest rate of 3.5% per annum for the first three months. After that, a variable standard rate of 1.5% per annum applies to balances up to 100,000 euros. Interest accrues monthly and can be tracked daily through the ADAC credit card app and online banking portal.
Steffen Jentsch, chief executive of Solaris, said the savings product was the “next logical step” in the partnership, with a stated aim of continuously expanding digital services for ADAC’s large membership base. Joost Greve, managing director of ADAC Finanzdienste GmbH, pointed to simple digital processes and security standards as the product’s defining priorities.
Expanding the embedded product suite
The savings account is not the only feature added to the ADAC card this year. Since May, cardholders have had access to a function called EuroAbruf, which allows customers to transfer up to 5,000 euros from their available credit limit directly to a personal bank account via SEPA Instant Credit Transfer. The process is fully self-service and subject to risk and authorisation checks. According to a survey cited by Solaris, 90.3% of participating cardholders said they were very satisfied with the additional card features, though the methodology and sample size were not disclosed.
The two additions together represent a pattern familiar in embedded finance: a card product used as a distribution anchor, with savings, credit access and payments layered progressively on top. This approach deepens the cardholder relationship and increases product revenue per user without requiring a full banking app relaunch.
Market and regulatory context
Solaris holds a full German banking licence, which gives it the regulatory standing to offer deposit-taking products directly rather than relying on a separate bank partner. That distinction matters in a sector where several BaaS competitors operate as technology layers over a licensed bank, creating additional counterparty risk and compliance complexity. The German deposit guarantee scheme (Einlagensicherungsfonds) applies to deposits held at Solaris, which will be relevant to any ADAC cardholder weighing the savings product against alternatives.
The competitive backdrop for BaaS-embedded savings is also developing quickly. Across Europe, several embedded-finance platforms and challenger banks have introduced savings products as a means of widening net interest margin, particularly at a time when central bank rate cycles have made deposit economics more attractive than they were for most of the low-rate decade. The promotional rate of 3.5% positions the ADAC product above the standard variable rate but below the leading easy-access rates available on the open market from specialist savings platforms, meaning ADAC cardholders who are already inside the app ecosystem are the primary target rather than active rate-shoppers.
The next milestone to watch is whether Solaris and ADAC Finanzdienste extend the product set further, potentially into investment or lending products, as the embedded suite deepens.
AI level 1 of 5: written by Darlyn Ho; AI helped with tone, structure or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean