
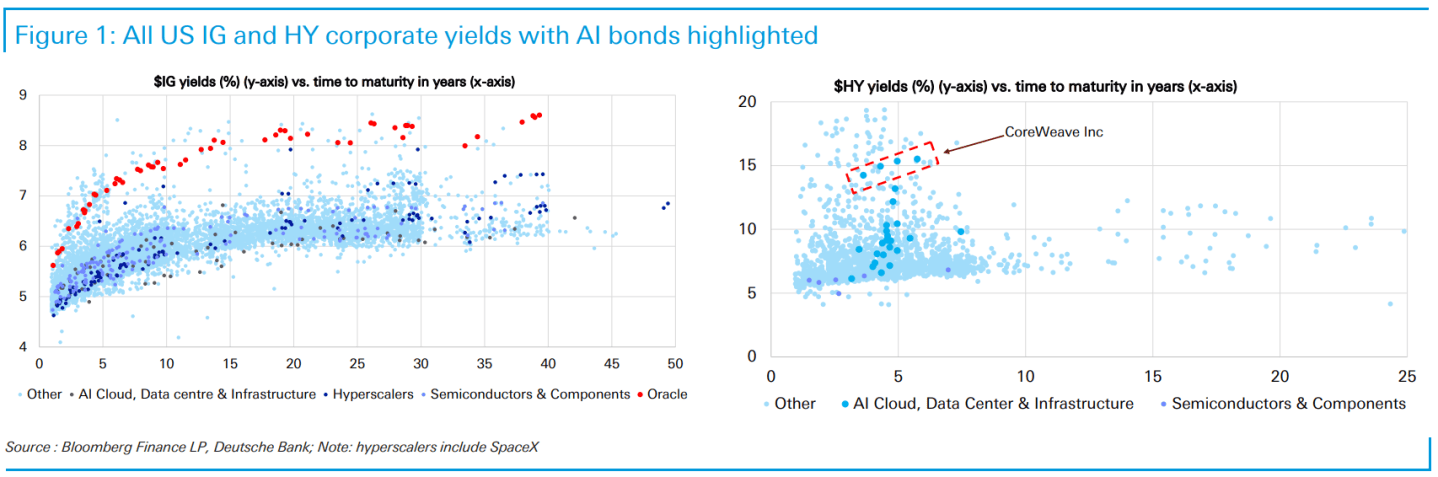
Shares in the AI “neocloud” provider CoreWeave fell 15.46% on Wednesday, and were down a further 5.62% in post-market trading, after venture capitalist Chamath Palihapitiya posted on X a chart showing the yield on CoreWeave’s bonds touching 15%. That’s an indicator that investors were demanding a steep premium for holding its debt. “Is the AI buildout creating a private credit bubble?” Palihapitiya asked.
At the same time, The Financial Times published an interview with CoreWeave co-founder and finance lead Brannin McBee in which he said he wanted to borrow even more money—from insurance companies. The insurance sector’s access to capital “is unlimited,” he told the paper. “Like, that’s all the money in the world that sits in the insurance tranche.”
CoreWeave’s vast debt pile has been the subject of controversy in the past. In 2025, a Fortune analysis of its financials concluded that the company had the potential to be “ground-zero for a future AI financial meltdown.”
Debt owed by AI service companies also made headlines recently when Oracle issued a “force majeure” citation to Blue Owl, the developer of a massive data center in New Mexico, over worries that the site won’t be finished when it is scheduled to come online in 2028—an indicator that customers might have the legal ability to walk away from their commitments if the weather changes against them. And Gartner estimates that 80% of neocloud providers will cease independent operations by 2030 because their revenues won’t cover their outgoings.
But the critics are wrong, according to Evan Schlossman, principal at Neostellar Capital Corp., a publicly traded VC fund that gives retail investors exposure to pre-IPO startup equity. (Neostellar bought a $25 million stake in CoreWeave in 2024 and sold 40% of it for a gain of $15 million in Q2 2025.)
CoreWeave has certainly taken on a lot of debt and lease commitments. According to its Q2 earnings release, it had operating lease liabilities of $16.3 billion and total debt of $35.6 billion. The company only made $4.6 billion in revenue that quarter, and its operating expenses exceeded its sales, leaving it with a net loss of $1.4 billion on the bottom line.
To put it simply, how will a company that makes no money pay back $52 billion in combined debt and lease commitments?
“Take or pay”
The short answer is that the company has $103.7 billion of “remaining performance obligations” (RPOs), 41% of which is scheduled to be paid to CoreWeave through 2028, its Q2 disclosure states.
That means CoreWeave is good for the money, Schlossman told Fortune.
RPOs are agreements to provide services that a company knows it will be paid for in the future—the revenue simply hasn’t been delivered yet. Companies are only allowed to disclose them if the agreements are noncancellable. They are “take-or-pay” contracts with “extremely high-credit-worthy customers,” Schlossman said.
A take-or-pay contract binds a customer to pay for the service even if they do not use it. CoreWeave’s major customers are Microsoft and OpenAI. Its top three customers (the third is undisclosed) generate 72% of its revenue in Q2, the company said.
It is highly unlikely that Microsoft might go bankrupt, leaving CoreWeave on the hook for unpaid bills, Schlossman said. In fact, one of the few ways that Microsoft can get out of the contracts is if an Oracle-style “force majeure” event prevents CoreWeave from delivering its services, according to the agreement between them.
That’s why CoreWeave can rack up so much debt—lenders can see their credit is being backstopped by non-cancellable RPOs from the type of companies that have a “tier-one balance sheet, that is underwriting this,” Schlossman said.
“We are confident in our backlog, which more than supports all of our debt obligations,” CoreWeave told Fortune. “98% of our revenue is from committed, take-or-pay contracts. We structure the majority of our financing so that cash flows from customer contracts repay the associated debt and generate additional free cash flow.”
“If there is something that goes wrong, I think you’re going to see that it’s going to matter significantly who owes you money”
While OpenAI’s balance sheet isn’t as rock solid as Microsoft’s, its RPO commitments to CoreWeave are also backed by RPOs which OpenAI has from other companies of Microsoft’s quality, Schlossman said: “A lot of these contracts are backstopped by other companies.”
“I understand how they’re going to get paid back on this, how much they’re going to make, and what are the specific risks associated with this,” he said.
Besides, even if OpenAI suddenly disappeared, the contracts it has for “compute” power are worth more now than when they were signed—implying that CoreWeave could sell that capacity to other customers.
Schlossman does admit that not every piece of the AI ecosystem will pass a stress test. Smaller companies backed by venture capital whose customers are also early seed-round venture-backed companies may not survive a downturn in the market.
“If there is something that goes wrong, I think you’re going to see that it’s going to matter significantly who owes you money, as it does in most businesses,” he said.
“Microsoft is ruthless and will eat CoreWeave for lunch”
CoreWeave’s critics are unlikely to be satisfied by that. Francine McKenna, the accountant and investigative journalist who has taught at The Wharton School and Cambridge and who now writes The Dig, a respected Substack about accounting, doesn’t believe Microsoft will deliver on CoreWeave’s RPOs if the demand for compute softens.
“If CoreWeave is counting on Microsoft to honor its contracts and bail them out of extreme debt and losses I have a bridge in Brooklyn I’d like to sell them. Microsoft is ruthless and will eat CoreWeave for lunch and throw bones to its dogs if it makes sense for them,” she told Fortune.
Microsoft declined comment.