Over the last several years, private equity firms have invested billions of dollars into the wealth management space, driving the industry’s rapid consolidation. Charlesbank Capital Partners, the New York-based middle-market private equity firm, has been one of the most active participants.
Charlesbank was established in 1998 after its founding team spun out of the Harvard University endowment. The firm’s investment strategy draws on its endowment heritage; it’s research-based, and it goes deep into the sub-sectors it has conviction in. It started a thematic initiative in wealth management in 2020 and made its first RIA play with Lido Advisors, which now has more than $46 billion in assets under management, in early 2021.
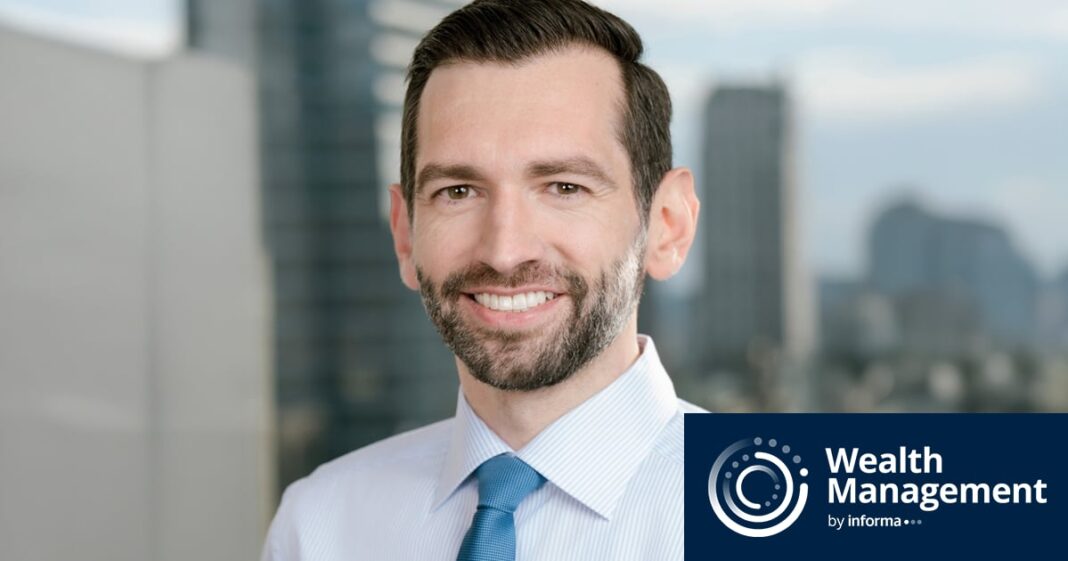
David Katz, managing director at Charlesbank, who helps lead the firm’s financial services investing strategy, recently spoke with Wealth Management about the thesis behind investing in the space, the bar being higher for wealth management platforms to compete, and how his firm is helping RIAs with artificial intelligence.
The following has been edited for length and clarity.
Wealth Management: When did Charlesbank first invest in the wealth management sector?
David Katz: Charlesbank is a private equity firm with about $24 billion in AUM, and we originally spun out of the Harvard University endowment back in 1998. I’ve been at the firm for 13 years now, overseeing our initiatives in the wealth management ecosystem, which includes a series of active investments. Our first platform investment was Lido Advisors, which is a high-net-worth RIA, in early 2021. We then invested in Pensionmark, which is now World Investment Advisors, in 2022. And then in January 2024, we invested in Rise Growth Partners, an RIA growth accelerator, which has four minority stakes in RIAs in partnership with Joe Duran. And then we also have a stake in the U.K.-based Perspective Financial Group, a UK IFA, which is basically the equivalent of an RIA.
Given the endowment heritage, we like to say that we’re very research-based in how we invest. We started a thematic initiative in wealth management going back to 2020.
WM: What is the thesis behind investing in the wealth management sector?
DK: There are obviously attractive financial characteristics to wealth management, but I think that undersells what is really happening. The wealth management ecosystem is a very large, fragmented industry undergoing a generational and technological transition. You have clients that are demanding more sophisticated responsibilities, advisors who increasingly are looking for better infrastructure around them, and then many firms, smaller firms need solutions around succession and scale.
What makes it especially interesting to us is that there are multiple ways to create a better business and not just through M&A. You can drive organic growth, recruiting, technology, investment capabilities, incremental services like tax and estate and the advisor experience. We think the next chapter is about building institutions rather than simply aggregating assets. If you look at the types of firms we’ve invested in, they’ve typically excelled at one or more attributes that I’ve talked about and been able to disproportionately take share and grow as a result of that.
WM: When you talk about this next chapter of building institutions, what do you mean by that?
DK: Even if you look back a decade ago, an investment thesis could rely much more heavily on industry tailwinds and consolidation, but now the bar is higher. It’s more around, why will this platform win? We’re looking at firms that have proven the ability to deliver durable organic growth, advisor productivity and recruiting, client retention across cohorts, strong management teams, the ability to integrate new hires and acquisitions and so on. What we’re really looking for is a platform that can provide capabilities that genuinely make clients and advisors want to be there. There are many different ways you can differentiate on those dimensions, but you need to. Increasingly, the focus is on building a firm that is a cohesive value-added partner to their advisors and serves their clients well, as opposed to simply a consolidation play.
The market is continuing to move much more toward cohesive institutions. And at least in terms of where we focused, that’s very much part of our thesis.
WM: How do you differentiate yourself from other private equity firms out there in the wealth space?
DK: One is industry experience and knowledge. We’ve been among the most active middle-market investors in wealth management, if you look at both directly through Charlesbank and through our partnership with Rise Growth Partners. We’ve seen different versions of what they’re going through, and we can help them based on our pattern recognition and experience. Done well, an investment partner can obviously provide growth capital to help the business get to the next level and/or deal with succession, but it’s really around a value-added partnership beyond capital.
We spend a lot of time helping build out management teams and recruiting leadership, investing in technology and infrastructure, building M&A teams, and supporting them in becoming thoughtful consolidators.
We do a lot of first-time institutional capital investing.
We generally like to partner with firms that have the core elements figured out. They have a clear strategy; they have some differentiation. They have a reason that we believe they could emerge as a real winner in the ecosystem, but maybe they haven’t figured out all the enablers so we can help them build out and deepen their management team. We can help them build an M&A function. We can help them scale referral relationships or diversify and grow new referral relationships over time.
WM: Do you have any recent examples of firms you’ve invested in, and helped grow
DK: We invested in Rise Growth Partners, and we made a $250 million capital commitment. In turn, Rise has been making individual investments. Those are all minority stakes in the next generation of platforms, if you will. So far, they’ve done four, and all of those are growth-oriented management teams. Our view is, there’s a type of firm that is maybe not looking for private equity capital yet or ever, but are very high-quality firms and could benefit from a little more operational and management involvement from folks who’ve been there and been in the trenches with them. That’s what Joe [Duran] ’s vision was, and they’ve executed that very well. The first firm Rise invested in, originally called Bleakley and now called One Point BFG, has been an incredibly impressive growth story both organically and through the recruiting of advisor teams.
If you take the other side of the ledger and you look at Lido, that was a slight majority deal. The next-generation leaders of that firm, Jason [Ozur] and Ken [Stearn], are running the business today and almost quintupled earnings over our hold period. That was very strong organic growth as well as acquisitions. And that business recapped last year, with HPS Investment Partners. We continue to be involved there, but have a smaller ownership stake. That business had some very strong referral partnerships where we helped them diversify those relationships and scale that business, as well as build out a deeper management venture around Jason and Kent.
WM: What are you doing in the way of AI?
DK: Within wealth management in particular, we have a center of excellence around AI use cases, given the number of companies we touch both directly and through Rise. Some of that is around cataloging the big use cases that our firms need and could benefit from. We use a combination of internal resources and third parties to help build those out, and then drive adoption by advisors and the individual portfolio companies. We’ve been very focused on picking the right parts of the workflow that can really be a combination of point solutions that’ll be quick wins as well as parts of the workflow that could be carved out and really redesigned with more of an automation lens.
Then there are also a bunch of initiatives around middle office efficiency, less about reducing headcount and more around just frankly reducing the rate of that growth.
WM: How does Charlesbank’s Harvard Endowment history come into play with the wealth space?
DK: One is, it influences how we invest; we’re very research-based, so we focus on thematic initiatives in spaces we know well and have a lot of conviction in, like the RIA ecosystem. You’ll tend to see us really go deep in the sub-sectors we like and often make multiple investments in sub-sectors we like.
The second is, we do have relationships in the ecosystem, and even though we are not part of an endowment, we have an interesting vantage point to the continued evolution and convergence of private markets and institutional investors, and just the opportunity to continue to bring institutional-caliber opportunities to private wealth management through to individuals.
WM: RIA M&A deal activity has slowed down significantly in the third quarter of this year. What are you seeing in terms of activity?
DK: In the past, it has been such a great space for investment. The near 100% recurring revenue, the highly sticky client relationships, 95% retention, organic growth tailwinds, both from new assets as well as just benefiting from market appreciation and the sheer amount of fragmentation in the industry that allows for M&A. That’s sort of the checklist, the wishlist, if you will, of what every private equity investor wants in a transaction.
It’s not surprising that it’s attracted a lot of capital, but I think at the beginning, folks were content just to invest in an average RIA. It could rely much more heavily on those industry elements and average growth, plus some consolidation. But today, the bar really is higher. The platforms want to see something that has proven value at the platform level for the advisor and the client, and it’s not just a collection of smaller firms or individual advisors who are doing their own thing. And advisors want to see what they’re getting from the platform in return for the economics and autonomy they’re giving up. And then that’s going to continue to be something investors focus on going forward at the platform level.
Because the investors at the platform level are looking for firms that are more cohesive and value added, in the past, you could do acquisitions, add-on acquisitions really just for scale. The prices of those have gotten bid up, and the competitive dynamics around those have gotten bid up, even if they’re not actually great firms or great books. It’s not to say that that’s going to dissipate. I think there’s still a lot of value in those types of firms at the right valuation. But we’re starting to see more bifurcation, if you will, of valuations and interest levels depending on whether the firm has a proven growth model, whether they have a strong Gen 2, or it’s really just a retiring group of producers.
As a result of that, sometimes there can be more of a mismatch in expectations, which will lead to some transactions and add-ons not happening immediately.
The prior world, where every small RIA kind of traded for a high multiple, almost irrespective of the fundamentals, I do think that is starting to evolve as people get more discerning and thoughtful about what they’re looking for.